
Author: Peng Cheng The explosive growth in AI (Artificial Intelligence) computing power demand is driving the rapid evolution of intra-data center interconnect bandwidth from 800G to 1.6T and 3.2T. Traditional pluggable optical modules have approached their physical limits in terms of power consumption control and signal integrity. Consequently, new technologies such as NPO (Near-Package Optics) and CPO (Co-Packaged Optics) have emerged. As the two major technical routes for next-generation optical interconnects, they have attracted widespread attention from the global industry.
The report "Photonics Packaging Heads Toward a $14.4 Billion Market by 2031" released by Yole Group on March 17 predicts that, driven by the strong demand from AI data centers and High-Performance Computing (HPC) scenarios, the global photonic packaging market will experience structural growth. It is expected to expand from approximately $4.5 billion in 2025 at a compound annual growth rate (CAGR) of over 21%, reaching $14.4 billion by 2031, tripling its market size over six years.
01 NPO and CPO: Shared Origins, Divergent Paths Both NPO and CPO are products of the evolution of optical interconnect technology toward higher integration. The two are not in a simple substitution relationship but represent the direction of technological evolution at different stages.
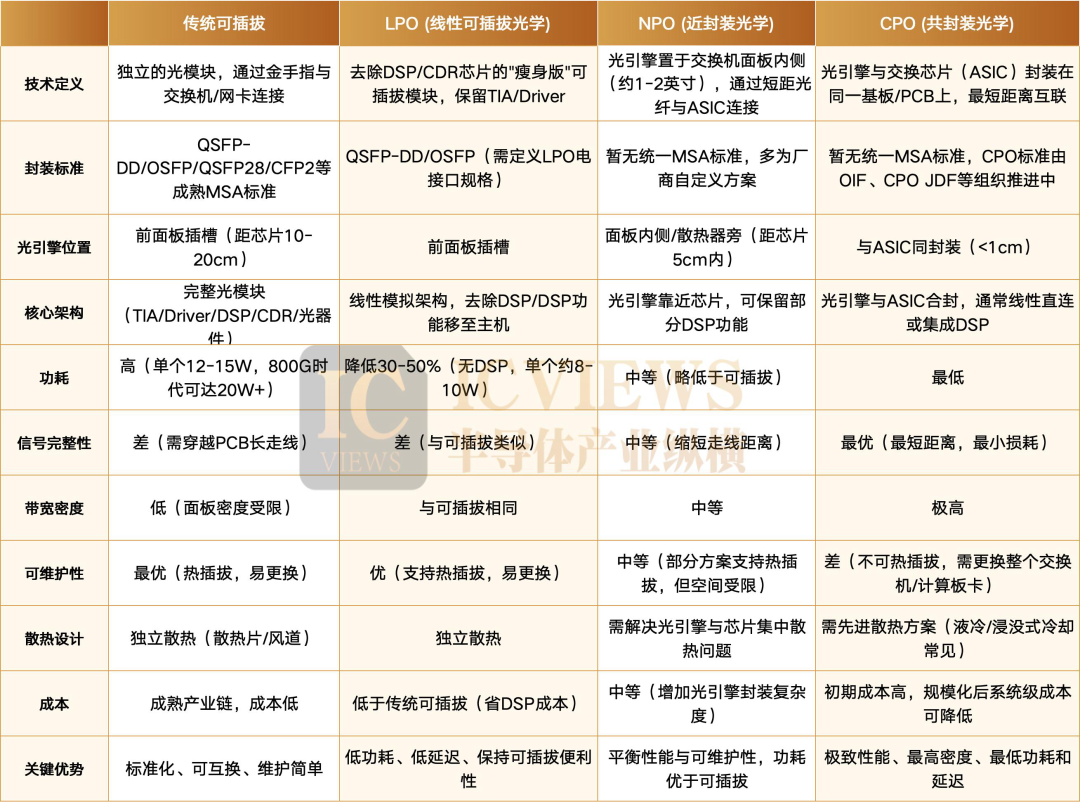
CPO (Co-Packaged Optics) is widely recognized by the industry as the "ultimate solution." Its core lies in utilizing 2.5D/3D advanced packaging technology to integrate the optical engine, responsible for electro-optical conversion, and the switch ASIC chip onto the same substrate or interposer. This reduces the electrical signal transmission path, which is over 100 millimeters in traditional pluggable solutions, to the millimeter level. This architecture completely eliminates signal loss caused by PCB (Printed Circuit Board) routing, allows for the omission of high-power DSP chips, reduces power consumption by 30%-50% compared to traditional solutions, and simultaneously achieves nanosecond-level ultra-low latency and single-channel bandwidth density of 3.2T+.
However, the commercialization of CPO still faces multiple challenges: it requires the integration of silicon photonics devices such as microring modulators (MRM) or Mach-Zehnder modulators (MZM) on the 3nm process node, and highly relies on advanced packaging platforms like TSMC (Taiwan Semiconductor Manufacturing Company) COUPE. It involves high technical complexity and low production yield. Meanwhile, the industry lacks unified standards, resulting in poor cross-vendor compatibility. Previously, the industry was generally concerned about the maintainability of CPO, but the scale-out switch reliability data released by Meta at the Optical Fiber Communication Conference (OFC 2026) presented a different conclusion: the tested CPO optical transceivers are more reliable than traditional pluggable products, with a more compact structure, smaller size, and lower power consumption. This finding effectively refutes earlier doubts.
NPO (Near-Package Optics), on the other hand, is a "pragmatic transitional solution" that balances performance with the current state of the industry. It retains the design of the optical engine as an independent unit, simply by mounting it on the switch motherboard close to the ASIC chip, reducing the electrical signal path to the centimeter level. This significantly lowers insertion loss while maintaining the replaceability and maintenance convenience of the optical engine. Because its manufacturing process is close to existing optical module technology, it does not rely on cutting-edge chip co-packaging capabilities and allows for decoupled design between the switch chip and the optical engine. NPO is more conducive to forming a mature ecosystem of multi-vendor collaboration and has become the preferred intermediate form for mainstream manufacturers before the large-scale promotion of CPO.
02 NPO Leads in Volume Ramp-Up, While CPO Gathers Momentum The differences in technical routes directly determine the speed of their commercialization processes and the differentiation of the market landscape. Currently, NPO has entered a period of rapid growth, while CPO is in its nascent stage but with astonishing growth rates.
The NPO market has entered a period of rapid growth, with large-scale commercialization officially kicking off in 2026. According to DataIntelo data, the global near-package optics market was valued at $3.8 billion in 2025 and is expected to grow at a CAGR of 19.3% from 2026 to 2034, reaching $18.6 billion by 2034.
North America has become the dominant region in the global near-package optics market, with revenues reaching $1.38 billion in 2025, accounting for approximately 36.2% of global total revenue. The region's leadership is driven by the concentrated presence of hyperscale cloud platform operators, including the world's top three public cloud service providers, which jointly operate hundreds of data centers across the United States, Canada, and Mexico. Silicon Valley and Northern Virginia, in particular, have emerged as major hubs for AI accelerator cluster deployment, where NPO technology is seeing the earliest and most aggressive adoption. North America is expected to maintain its lead until 2034, with a CAGR of 18.7% during the forecast period, driven by continuous reinvestment in next-generation data center infrastructure by cloud-native and enterprise operators. The Asia-Pacific region was the second-largest regional market in 2025, accounting for about 31.5% of global revenues, and is projected to achieve the fastest regional CAGR of 21.4% by 2034. In 2025, Europe accounted for 22.4% of the global near-package optics market share, and its CAGR is expected to reach 17.8% by 2034. Germany, the UK, France, and the Netherlands collectively hold the major share of European demand, benefiting from significant colocation and hyperscale data center clusters in Frankfurt, London, Amsterdam, Paris, and Dublin.
The CPO market is still in its nascent stage but with astonishing growth rates. Yole predicts that by 2031, transceivers alone will drive $8 billion in photonic packaging demand, while CPO-driven demand will surge from near zero currently to approximately $5 billion. LightCounting forecasts that the CPO market size, including scale-up and scale-out scenarios, is expected to reach $10 billion by 2030; Coherent (COHR.US) further revised its forecast upward to $15 billion at OFC 2026.
03 Global Vendor Layout: Domestic Players Lead in NPO, Giants Bet on CPO Based on their own technological accumulation and market positioning, global technology vendors have carried out differentiated layouts on the two routes. Among them, Chinese vendors have established a significant leading advantage in the NPO field, while international chip giants dominate the technological evolution of CPO.
NPO: Domestic Vendors Secure Large Orders, Continuous Technological Breakthroughs Materialize On April 7, 2026, Google officially placed an order for 12 million NPO optical modules, with a total value of approximately 12 to 15 billion RMB, specifically for the scale-up layer chip-to-chip interconnects of its next-generation TPU v7/v8/v9 supercomputing clusters. Zhongji Innolight and Eoptolink, two domestic leading companies, secured 60% and 40% of the share respectively, taking the entire order.
Even earlier, domestic vendors had already achieved multiple breakthroughs at the technical level.
On March 2, 2026, the industry's first 3.2T NPO (Near-Package Optics) product, independently developed by HG Genuine Optics, a core subsidiary of domestic optoelectronics industry leader HGTECH, has taken the lead in completing landing applications for top industry customers. This 3.2T NPO optical engine adopts silicon photonics and packaging technologies, with a single optical engine achieving 3.2Tbit/s transmission (integrating 32 channels of 100G). This solution does not use traditional DSP chips but utilizes linear direct drive technology. It has now begun to be applied to some customers and is planned for broader application promotion in 2026.
Accelink Technologies showcased the world's first 3.2T silicon photonics single-mode NPO module at OFC 2026. This product completed sample testing several months ago. More notably, during the same period, Accelink Technologies completed the full-system verification of 3.2T NPO at leading domestic CSPs, becoming the first optical module vendor in the industry to achieve this breakthrough. This also marks the formal transition of this technology from the laboratory to large-scale engineering implementation.
Higon Optronics showcased 6.4T NPO silicon photonics engine technology at OFC 2026. By stacking the EIC and PIC through advanced silicon photonics packaging technology, it reduces the engine size and shortens the electrical signal path. The engine features a single specification of 16x200G transceiver chips, with a lateral dimension of less than 8mm, and can be applied to high-density optical interconnect product fields such as 3.2T/6.4T NPO, OSFP-XD PCIe, and XPO.
CPO: Chip Giants Lead, Domestic Vendors Accelerate Follow-up NVIDIA is the most aggressive promoter of CPO technology. At the GTC 2025 conference, NVIDIA released Quantum-X (IB network) and Spectrum-X (Ethernet) silicon photonics co-packaged chips and three switch products, choosing the microring modulator (MRM) technical route and deeply cooperating with TSMC to develop 3D stacked silicon photonics engines. It plans to deliver InfiniBand CPO systems in the first half of 2026 and deploy Ethernet CPO products in the second half, while laying out CPO on both the switch side and the GPU side, ultimately achieving optical connections between GPUs and NVSwitch chips.
Broadcom, on the other hand, delivered the industry's first 51.2Tbps CPO Ethernet switch, Bailly, in March 2024. It integrates eight 6.4Tbps optical engines with the Tomahawk 5 chip, claiming a 70% reduction in power consumption. Technically, it chooses the Mach-Zehnder modulator (MZM) route while simultaneously laying out MRM. Its CPO production line will enter a critical mass production stage in the second half of 2026, with an expected monthly capacity reaching the thousands in the fourth quarter. Should customer adoption progress smoothly, monthly output is projected to rise to tens of thousands by Q1 2027.
Domestic vendors are also actively laying out the CPO track: Ruijie Networks released a 25.6T CPO switch in 2022 and demonstrated a commercial interconnect solution for a 51.2T CPO switch based on Broadcom's Bailly chip in September 2025; H3C launched the industry's first single-chip 51.2T CPO silicon photonics switch supporting 64 800G ports in 2023, with a focus on optimizing liquid cooling and air cooling thermal designs.
It should be noted that the large-scale application of CPO still needs to overcome many practical challenges: the cost for a single optical engine unit ranges from $35,000 to $40,000, and high-density integration brings severe thermal challenges, requiring supporting liquid cooling systems. Moreover, the optical engine is solidly integrated with the main chip; once a failure occurs, the entire board needs to be replaced, resulting in poor maintainability and flexibility. In addition, there is a lack of interoperability consensus between NVIDIA's COUPE solution and Broadcom's FOWLP solution, and the absence of industry standards has also delayed the popularization speed of CPO.
04 Application Scenario Differentiation: Different Choices for Scale-up and Scale-out The competition between NPO and CPO is not a zero-sum game. The two will complement each other in different application scenarios and time stages, jointly supporting the upgrade demands of AI computing clusters.
From the perspective of scenarios, the demand differences between scale-up (intra-rack GPU interconnects) and scale-out (inter-rack/data center interconnects) determine the choice of technical routes: in the scale-up scenario, as the single-channel rate evolves to 400G, the copper cable transmission distance will be shortened to less than 1 meter. Relying on its ultimate bandwidth density and low power consumption advantages, CPO will be the first to enter the intra-rack interconnect field. In the scale-out scenario, relying on better compatibility and maintainability, NPO becomes the preferred transitional solution for high-end data centers between 2025 and 2027.
From a time dimension perspective, in the short term, NPO will take the lead in large-scale volume ramp-up. It balances performance and compatibility, circumvents the core chip and advanced packaging barriers of CPO, allows for a smooth transition of the existing industry chain, and is also a pragmatic choice for domestic data centers and cloud vendors for "performance upgrade + controllable cost." In the medium term, CPO will enter a period of high-speed growth. As chip giants like NVIDIA and Broadcom promote mass production, and packaging platforms like TSMC COUPE mature, CPO will establish its core position in hyperscale AI clusters. Especially when the single-port rate breaks through 3.2T, the power consumption advantage of CPO will become irreplaceable. In the long run, CPO will become the mainstream, but NPO will still have room for survival. The AI computing power market is layered in a pyramid, with diverse demands from edge computing to supercomputing centers. Although CPO represents the ultimate direction of technology, NPO will still exist in the long term in specific scenarios such as mid-tier data centers that require frequent maintenance.
05 XPO Emerges Just as the route dispute between NPO and CPO is intensifying, on March 11, Arista, together with more than 45 industry partners, officially released the XPO (Ultra-High Density Pluggable Optics) white paper, proposing a new pluggable optical module standard for next-generation AI data centers, bringing a third option to the industry.
XPO is specifically designed for the ultra-high bandwidth, high density, and high power consumption demands of 100,000-card GPU clusters. A single module can provide 12.8Tbps bandwidth (64 channels × 200Gbps), integrating a liquid cooling cold plate to support 400W+ power consumption. It achieves a 204.8Tbps switching capacity within 1 OpenRack Unit, achieving a 4x front panel density improvement compared to the existing OSFP standard. It not only retains the O&M convenience of traditional pluggable modules but also takes into account the high-performance advantages of CPO/NPO, capable of covering the full-scenario demands of scale-up/scale-out/scale-across (inter-data-center).
Currently, domestic vendors such as Zhongji Innolight, Eoptolink, and Linte have released related XPO products. Some Chinese vendors have even joined the ranks of founding members of the XPO MSA, becoming the formulators of the new generation of standards. The XPO solution has been recognized by mainstream customers such as Microsoft and Dell, and is expected to form a tripartite market pattern with NPO and CPO in the future.
The competition in AI computing clusters is shifting from "simply stacking computing power" to "the competition of network efficiency," which puts forward more comprehensive and stringent requirements for optical interconnect technology. The rapid implementation of NPO, the technological breakthroughs of CPO, and the sudden rise of XPO are jointly promoting the innovation and transformation of the optical interconnect industry. In the future, the three technical routes will find their respective positions in different scenarios, jointly supporting the continuous upgrade of global AI computing infrastructure.