
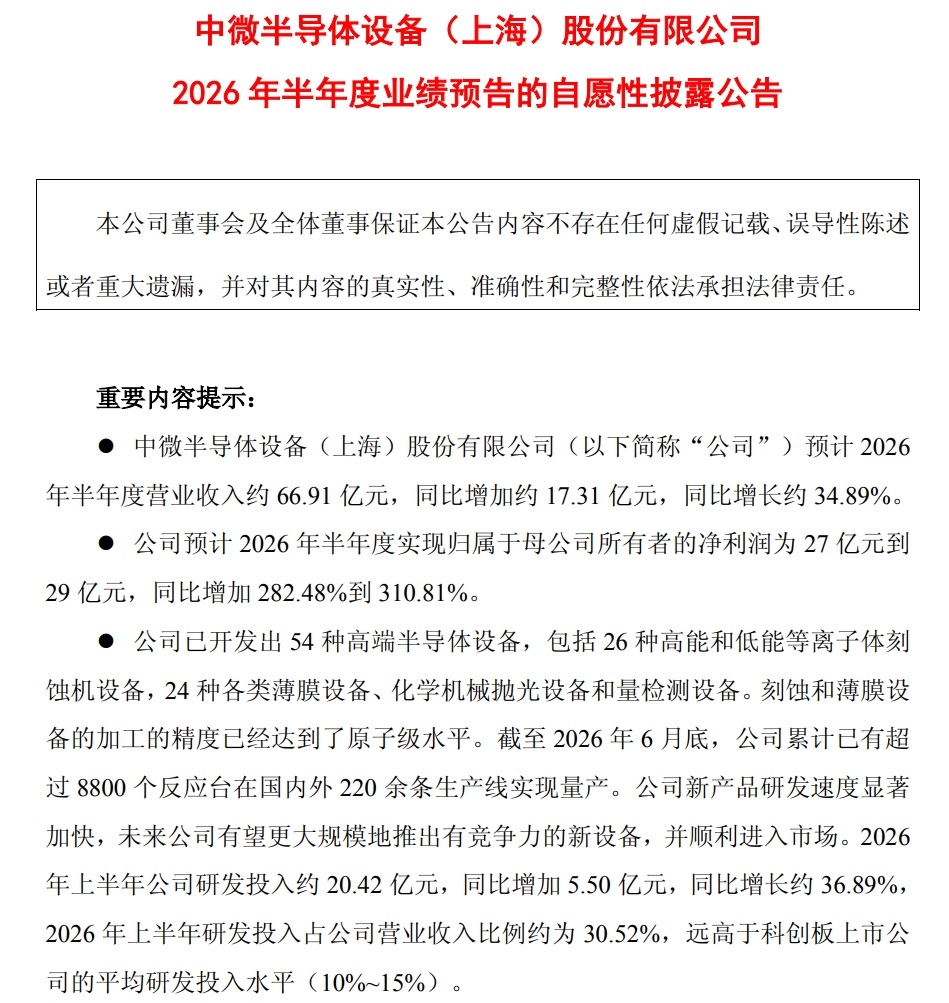
On August 3, AMEC (Advanced Micro-Fabrication Equipment Inc. China), a leading domestic semiconductor equipment manufacturer, released its 2026 semi-annual performance forecast. The company expects to achieve an operating revenue of approximately 6.691 billion RMB in the first half of the year, representing a year-on-year growth of about 34.89%. Even more striking is its profitability performance: the net profit attributable to shareholders of the parent company is projected to reach a high of 2.7 billion to 2.9 billion RMB. Compared to 706 million RMB in the same period last year, this represents a staggering year-on-year increase of 282.48% to 310.81%. Even after excluding the impact of non-recurring gains and losses such as external equity investments, the net profit attributable to shareholders of the parent company after deducting non-recurring items is expected to reach 1 billion to 1.2 billion RMB, a year-on-year growth of 85.61% to 122.73%, indicating a leapfrog growth in the profitability of its core business. On a quarterly basis, calculated based on a Q1 net profit of 930 million RMB, the company's net profit for the second quarter alone is expected to surge by 90% to 111% quarter-on-quarter, demonstrating an extremely strong growth momentum.
There are two major highlights in this performance forecast that are particularly worthy of attention.
First, the nearly "cost-no-object" R&D investment is the core key to the company's sustained technological leadership. In the first half of the year, AMEC's R&D investment reached approximately 2.042 billion RMB, a year-on-year increase of 36.89%. The R&D investment accounted for a high proportion of 30.52% of operating revenue, far exceeding the 10% to 15% average level of companies listed on the STAR Market. This intensive R&D investment has already yielded fruitful results. The company has developed 54 types of high-end semiconductor equipment, with the processing precision of its etching and thin film deposition equipment reaching the atomic level. More importantly, the R&D speed for new products has significantly accelerated. While it previously took three to five years to develop a new piece of equipment, it now takes only two years or even less. This has laid a solid foundation for the company to launch highly competitive new products on a large scale and rapidly capture the market in the future.
Second, the dual-driven strategy of platformization and external M&A has broken the ceiling for future growth. The company is accelerating its three-dimensional growth strategy that combines "organic growth" with "external expansion." The recent successful acquisition of Hangzhou Zhonggui has brought high-end Chemical Mechanical Polishing (CMP) equipment into its portfolio. This forms a clear complement to the company's existing dry process equipment, such as etching and thin film deposition equipment, marking a crucial step towards becoming a platform-based and group-oriented enterprise. Furthermore, Gerald Yin, Chairman of the Board, has set an ambitious goal: to cover at least 60% of high-end semiconductor equipment within the next five years, with an overall capacity planning of no less than 70 billion RMB.
Future Outlook
AMEC is ushering in unprecedented development opportunities, the most important catalyst of which is the IPO and subsequent large-scale capacity expansion of CXMT (ChangXin Memory Technologies, Inc.), a leading domestic memory chip manufacturer.
As the only domestic IDM leader with the capability for large-scale independent R&D and production of DRAM, CXMT plans to convert the vast majority of its 29.5 billion RMB raised from its STAR Market IPO directly into equipment procurement orders. The equipment purchase and installation fees alone amount to approximately 22.066 billion RMB. As its core equipment supplier, AMEC has achieved batch supply and deep synergy across multiple categories of equipment, including plasma etching equipment and thin film deposition equipment. It will clearly benefit from the equipment procurement wave driven by CXMT's new wafer capacity additions in the coming years. Institutions predict that CXMT plans to add 50,000 to 60,000 wafers of wafer capacity in 2026, corresponding to an equipment procurement value expected to exceed 5 billion USD. As the domestic leader in the two high-value segments of etching and thin film deposition, AMEC has an extremely high certainty of securing orders.
Conclusion
AMEC's 2026 first-half performance forecast demonstrates its strong competitiveness and growth potential in the field of high-end microfabrication equipment. Relying on the technological barriers built through intensive R&D investment, the vast growth space brought by the platformization strategy, and the certainty of deeply benefiting from the capacity expansion of domestic memory giants like CXMT, AMEC is standing at the starting point of a new round of high-speed growth. Its 2035 vision of "becoming a first-tier global semiconductor equipment company" is becoming increasingly clear and realistic.